Borrower Meetings
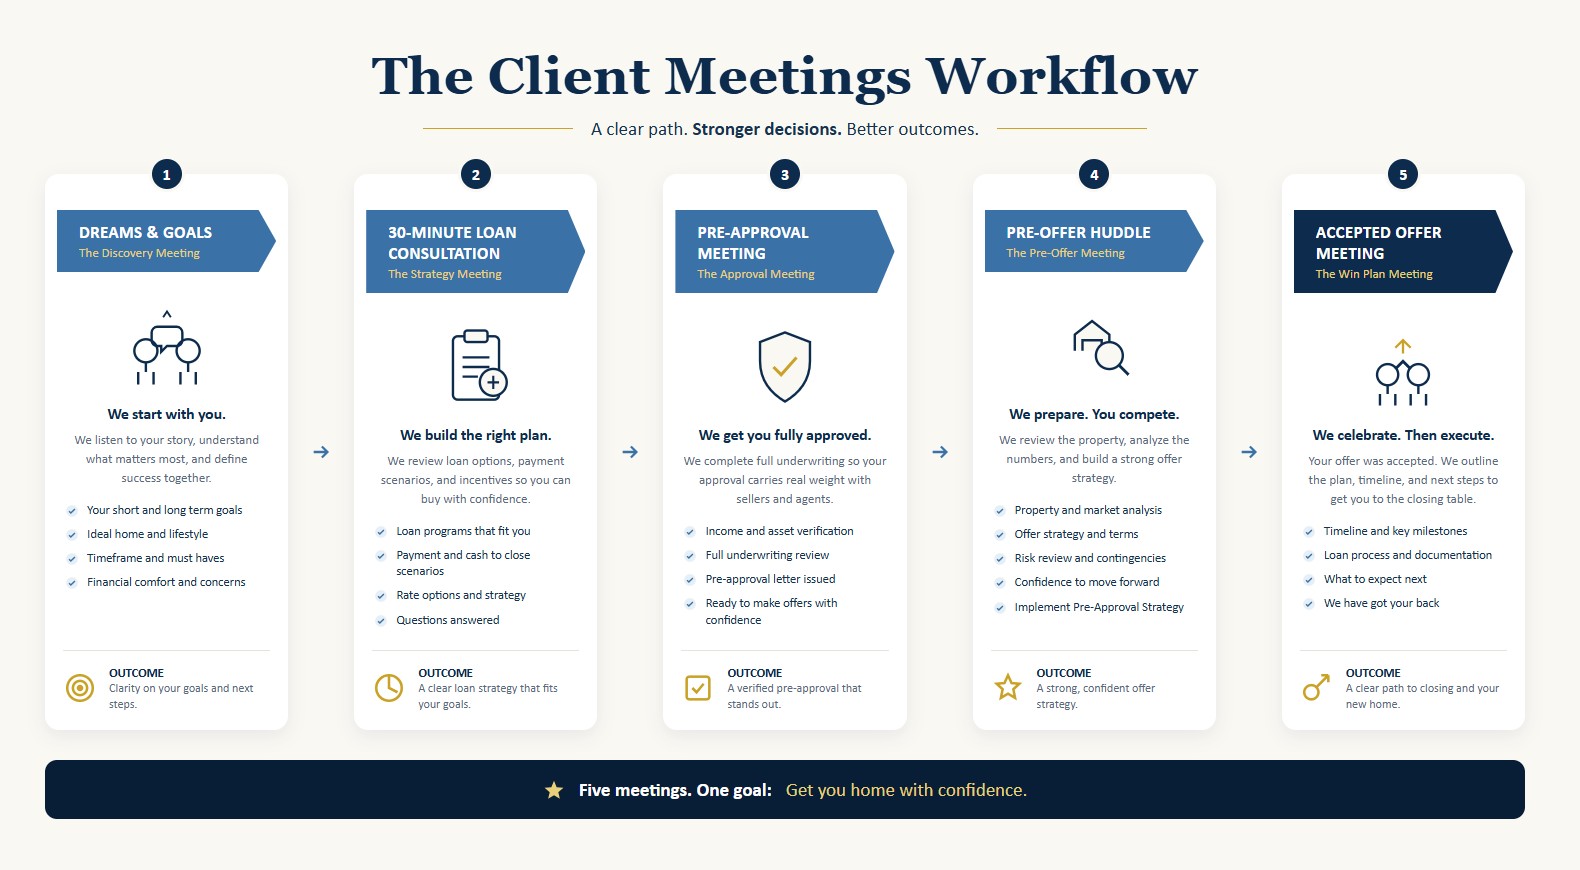
Dreams & Goals
Good morning/Good Afternoon, Mr. Client. It's great to meet you.
Thank you for taking the time to meet with me. I'm looking forward to getting to know you and learn about your goals.
We've got a very simple process, and I'm going to walk you though each step and make sure I answer all of your questions.
I will also text you my contact card. Please save it to your phone when you get it.
Who referred you?
Or
How did you hear about me? Skip if you know.
So, how did you meet the (Agent's Name)?
You're in great hands with (Agent's name). If I were buying a home in that area, I'd absolutely use him/her. They're going to help you identify the right home, negotiate the best deal, and ensure that you're protected along the way. He/She always puts his/her clients first.
So tell me your story…
Have you thought about a monthly payment budget?
What is your biggest reason for wanting to buy now?
What is your time frame to do this?
Where do you want to buy?
What type of property do you want to buy?
What is your current housing situation? Do you have a lease?
Have you owned a home in the last 3 years?
What is your current home worth?
How much do you owe on it?
Have you served in the US Military? Do you want to use your VA eligibility?
Are you married?
Do you have kids? What are their ages?
Will anybody else be on the loan or on title to the house?
Has anyone reviewed a Pre-Approval Strategy with you?
Did anyone explain how the mortgage market works?
Has anyone reviewed the tax advantages of home ownership?
Did anyone explain what a buydown is or the types of buydowns?
Did anyone review what a seller concession is?
Has anyone reviewed the difference between a Condo and a PUD?
Income
What type of work do you do?
Are you paid hourly, salary, or self-employed?
What is your annual income?
Are there any employment gaps in the last two years?
Do you receive Bonus/Commission/Hourly income?
Do you have any other sources of income?
How many years have you been at your current job?
For Self-Employed
What is the name of your business?
Home Long have you been in business?
Type of Business?
Number of Full-time Employees/Contractors?
Do you have separate personal and business accounts?
Assets
How much have you set aside for down payment and closing costs?
Are the funds liquid?
Do you have a 401k?
Do you plan on receiving any gift funds?
Debts
Revolving. Installment. Spousal or child support. Union Dues.
Have you Co-signed on a loan for someone?
Credit concerns or past challenges?
Wealth Team
Tax Planner
Financial Planner
Estate Planner
Insurance Planner
Next Step
So, our next step is the 30 Minute Loan Consultation.
Before we meet, I’ll build your Clear Mortgage Plan so we can review the financing strategies that make the most sense for you.
We’ll go over the right purchase price range, current interest rate range, what your total monthly payment would look like, and exactly how much cash you’ll need for closing.
Most importantly, we’ll tie everything back to your goals, rather than just looking at a generic loan scenario.
I’ll also share some financing strategies that may help you in today’s market and walk you through our Pre Approval Strategy, which is designed to put you in the strongest possible position to win the home when you find it.
We’ll also cover what to expect once your offer is accepted, so there are no surprises along the way.
After our call today, I’ll email you a link to your customer questionnaire so we can start working on your Pre Approval.
Does 2:00 p.m. Tuesday work for your 30 Minute Loan Consultation?
And if you have any questions before we meet, please don’t hesitate to reach out. I’m excited to help you through the process.
Thanks again for your time.
Rate Question: Quick Version
That's a great question, and we're going to cover that in your Mortgage Plan Consultation, which we'll get scheduled before we wrap up today.
First, let me get your questionnaire over to you so I can understand your complete situation. Then I can give you an accurate answer based on your financing options, rather than just throwing out a rate that may or may not apply to you.
Rate Question: Full Version (When they really push)
Absolutely. I understand the interest rate is really important.
The good news is I'm a mortgage broker with access to over 200 lender relationships. That means I work for you, not for one particular lender.
So when we talk about your rate, it's not really about "our rate." It's about finding the best combination of rate, cost, and loan strategy for your specific situation from the lenders I work with.
Your interest rate is based on several factors, including the loan program, down payment, credit profile, property type, loan amount, and how long you expect to keep the financing.
That's why I don't want to just throw out a number that may not actually apply to you.
What works best is to complete the quick questionnaire and then we'll meet for your 30 minute Loan Consultation.
Before that meeting, I'll build your Clear Mortgage Plan so I can show you an accurate rate range, your estimated payment, cash needed to close, and the financing strategies that make the most sense for your goals.
30 Minute Loan Consultation
So we will review
-Sales Price
-Monthly Payment
-Total Investment
-Today's rate range
-Review The Pre-Approval Strrategy
-Review Mortgage Under Management - MUM
-And answer all your questions
At the end of you will a clear mortgage plan, and your questions answered. So let's start with your questions...
Write down all their questions
Great questions. Do you have any more questions?
Don't answer the questions until our have all their questions. That way, you stay in control.
At end of Loan Consultation, Get THE COMMITMENT!
Was this a good use of your time? Do you have any more questions?
Is there anything that would prevent me from being your lender?
"I need to talk to other lenders"
"Great, what are you hoping to find from another lender?"
"I need to shop around"
Great, are you shopping for the lowest rate or the lowest cost?
Are you aware the lowest rate typically has the highest cost? Would you like me to show you how that works?
What rates are you seeing out there? Where did you see those rates?
"My realtor told me to talk to 3 people"
Great, what do you hope to get from talking to 2 other people?
Are there any questions that I haven't answered?
"I'm waiting for rates to drop."
I had a client last spring who waited six months. The purchase price went up $22,000. They paid more even with the lower
rate.
What would rates need to look like for this to make sense today?
"Call me back in six months."
No problem. Can I ask what's changing in six months? I just want to come back with the right information at the right time.
"I can't afford it right now."
Is that a down payment concern, a monthly payment concern, or both?
Those are two very different problems, and at least one I can probably help with right now.
"Okay, I still really want to shop around?"
Great, what I'll do is keep everything where it is right now.
If I could just ask two things?
Make sure you tell your realtor I took great care of you and the second thing is whenever you see whenever you find the lowest rate you can, send it to me let me see to see if I can beat it.
Either I'll show you it's the best thing I've ever seen or show you how we can beat it.
Does that sound fair?
And when you are ready, we can finish your Pre-Approval and implement our Full Pre-Approval Strategy to help you win the home.
Can't you just give a Pre-Approval now?
You see, to continue with the full pre-approval, we have to invest resources of my team, time and money, implement our full Pre-Approval Strategy, and use our reputation to help you win the home. We are glad to do that for you when we know that we are working together.
How about I follow up in a week to see how you're doing?
Objections and Rebuttals
Why should I use you and/or your company?
That's a great question, I'm glad you asked =...
Beat 1: Lead with the differentiator
You're not just hiring Barrett Financial. You're hiring me.
Barrett has been in business for over 22 years and we are the largest mortgage broker in the country by volume. We closed almost 10 billion dollars last year, so the processes, systems and resources are established.
I've been doing this for over 20 years. I've seen enough deals to know where they go sideways before they do, so when I partner with clients early in the home buying process, we catch the issues instead of finding them two weeks before closing.
I work as a broker, not for a bank. That means I work for you, not for one particular lender.
So when we talk about rate, it's not about "our rate."
It’s about what I have found for your situation out of 199 lenders.
Beat 2: What that actually looks like
My job breaks down into four parts..
- Understanding what you're actually trying to accomplish.
- Build the financing strategy around that.
- Walk you through the process step by step.
- And this is the part almost nobody else does, and it's about 60% of my overall job - managing your mortgage after you close.
I'm stay in your corner and proactively help you navigate whatever comes next — your family growing, rates moving, your overall debt, refinancing opportunities, when it might make sense to buy again or sell.
You're not going to be figuring that out alone and hoping to remember to call me. I'm going to be the one reaching out to you.
(pause here, check in: )
Have you worked with a loan officer before who stayed in touch after closing?
Beat 3: Hand it back
So what matters to you most, the payment, the timeline, or something else?
Ask for Referrals
The Ask for Everyone
Do you know any friends, family, or co-workers who are looking to buy, sell or refi?
At the beginning of the transaction, once rapport is built, I say something like:
Hey, Steve is an incredible Realtor. How did you meet him?
They usually share the backstory, follow with:
You’re in great hands.
He’s one of the best, and he runs his business almost entirely by referrals and reviews.
If you don’t mind, once you see how good he really is — and you will — think of two people who shouldn’t still be renting or who might be ready for their next home.
Then before we close, we can surprise him with a couple of referrals.
At the end of a transaction
Thank you for letting us be part of your home-buying journey.
Can I ask a couple of favors? Next time friends or family bring up buying a home, or ask about your experience would you mention that you "Got a Guy." That actually, you have a team.
I'd really appreciate that.
So I have to ask, do you have anyone right now that would benefit from Your Team?
[If response is "Nobody comes to mind"]
Totally understand.
Lastly, do you mind if I send you the link my Google Business Page. I would really appreciate and honest review.
Thank you so much!
Ask them to complete the Application - “So that” Method
Hey Mr. and Mrs. Client, we have a very simple process.
I’m going to email you a quick questionnaire for you to complete that I stated on your behalf.
That way we will have the information so that we can help build a clear mortgage plan.
Asking for Documentation - The “So that” Method
Hey client, is there anything that would prevent you from uploading your documents tonight by 10:00 p.m. so that I can ensure that we're able to verify everything and get you Pre-Approved before your find your new home?
Pre-Approved an looking group text - The “So that” Method
Hey I'm so glad that you're fully pre-approved I'm going to add us to a group text.
When you're looking at homes you can text me the address so that I can update the numbers and make sure the monthly payment and cash to close still meet our goals.
Temporary Buydown - Seller subsidizes your mortgage for 2 or 3 years
What if I told you the seller could pay part of your mortgage payment for the next year or two? It's real, and it's called a temporary buydown.
Here's how it works. As part of the negotiation, the seller agrees to pay a lump sum at closing. That money doesn't go to you directly. It goes into an account with your lender.
That account is used to lower your monthly payment for the first two years, or even three years of your loan.
So instead of paying your full rate right away, you might pay two percent less in year one and one percent less in year two before it steps up to your normal rate.
This gives you breathing room. Maybe you're expecting your income to grow. Maybe rates come down and you refinance before the buydown even ends. Either way, you get lower payments when your budget is tightest, right after you move in.
Here's something a lot of buyers don't realize. Because this money is collected and applied by the lender at closing, it may create an additional tax deduction beyond what you'd normally get from mortgage interest. Every situation is different, so definitely check with your tax advisor on how it applies to you.
If you're working with a seller who has some room to negotiate, ask me about structuring a temporary buydown instead of a straight price cut. It could save you real money in year one. Reach out and let's run the numbers.
Pre-Approval vs Pre-Qulification
First, thank you for calling. We’re really excited to help.
Our approach is pretty simple. There are really two steps.
Step one is the Pre-Qualification. This is where we take a 30,000-foot view of your situation. I’m going to ask you a lot of questions about your income, assets, debts, credit, goals, and what you’re looking to accomplish.
I don’t need to run your credit or collect all of your documentation. The goal is to figure out, generally, whether buying a home makes sense for you and what that might look like.
I’ll show you different purchase prices, down payment options, estimated monthly payments, and help you understand what you can realistically afford.
At the end of that conversation, you should be able to say, “Yes, I think I’m ready to do this,” or “Maybe I need to work on a few things first.”
And either answer is perfectly fine.
Once you know you’re ready, the next step is the Full Pre-Approval.
That’s when we’ll collect your documentation, run your credit, verify your income and assets, and submit your file to underwriting. We’ll know your maximum purchase price, your down payment options, your monthly payment, and, most importantly, we can identify and address any potential issues before you’re out shopping for a home.
That allows us to implement our Pre-Approval Strategy, which is designed to put you in the strongest position possible when you find the right home and "win" the home.
It also eliminates the horror stories. A lot of those problems happen because something wasn’t discovered or addressed until after they were already in contract.
We want to find those things before you’re competing for a house, not after you’ve fallen in love with one.
Today we can start with making sure I answer all your initial questions and then I will ask alot questions so I better understand what you are trying to achieve.
Then we will have another meeting to review your options. Instead me telling you, I will be showing you with a software that make everything very clear. It’s basically a website with loan options that design exactly for you.
I found a lower rate online, can you beat it...
That’s a great question!
I'm a broker, not a bank, which means I work for you, not the lender. So when we talk about rates, it's not about what I'm offering; it's about what I found.
Online rates are the best-case scenario for the beast case loan scenario. Rates can vary based on several factors, such as lock period, credit score, loan amount, down payment, the type of loan you choose, and sometimes the time and day you received your quote.
I built my business on never quoting inaccurately. And if you ever see a number out there we didn't talk about, bring it to me. There's almost always a reason, and we'll look at it together.
Another approach:
I don' t think I can match that.
Let me ask you something...If i could, who would you go with?
Let them tell, why they would go with you. Now they have told why, to them, you are better. Learn into that.
So you said that, A, B, C,. Do you believe that A, C & C are worth the difference?
Follow Up Questions:
Has anyone taken the time to explain how mortgage-backed securities work, lock periods, or Loan Level Price Adjustments?
Has anyone aligned your anticipated hold period with the breakeven of paying points?
Has anyone explained the difference between permanent and temporary buydowns to you? O how to use a Seller Credit?
I would like to take a few minutes to discuss your situation and provide an accurate quote that aligns with your goals. I will combine several options into an online comparison that shows each option's total cost and payment schedule.
I will compare different hold periods so you can make an educated decision on the right option for you. Instead of me telling you, the comparison allows me to show.
Can I ask you a few questions now?
Start Dreams and Goals Survey
"Seller Mortgage Subsidy" (Temporary Buydown)
Has anyone showed you how the seller can pay part of your mortgage payment for your first two or three years? This strategy is the only one that allows a seller to effectively transfer money from their account to yours.
Many people have heard of it, most don't understand the power of it.
I call it a Seller Mortgage Subsidy, you may have heard it called a temporary buydown.
Here's how it works. As part of the negotiation, the seller agrees to pay a lump sum at closing. That money doesn't go to you directly. It goes into an escrow account with your lender.
That account is used to lower your monthly payment for the first year, two years, or even three years of your loan. So instead of paying your full rate right away, you might pay two percent less in year one and one percent less in year two before it steps up to your normal rate.
This gives you breathing room.
Maybe rates come down and you refinance before the buydown even ends. Also, if your refinance or sell before before the buydown period is up, you get a any more left over. Your lender will either reduce your loan amount by what is in the escrow or send it to you in a check.
Either way, you get lower payments when your budget is tightest, right after you move in.
Here's something a lot of buyers don't realize. Because there is a closing cost to pay for this, it may create an additional tax deduction beyond what you'd normally get when you write off your closing costs. Every situation is different, so definitely check with your tax advisor on how it applies to you.
Often, this is a better strategy than of a straight price cut. Let me show you the numbers.
MBS Highway
Most lenders would like you to believe there is a single rate you qualify for.
But the reality is there's an entire range of rates that you qualify for. My role isn't to select that rate and to tell you what you get.
It's really to guide you through the various options and help you walk through those so you can select the rate that best fits your scenario.
With that being said, let me share my screen and show you a bit about mortgage rates and where they come from.
Show MBSHighway
So what you're looking at now is the current mortgage-backed security chart. This is where interest rates come from. Now, many lenders would also like you to believe they have a monopoly on great rates.
But here's the reality. We all get our gas from the same pump. This is where it comes from. Now, I want to point out a couple of things I think are important to you, because right now, this probably just looks really super busy. So, green is good, red is bad.
And I want to point out something to you. So, I know we're already in April, but back on February 27th, and I want to get specific here because it's important to me that I establish that knowledge
That's why it was so cheap to borrow money back then. So, fast forward to today, and I'm going to go back to six months because I want to I want you to understand this.
Fast forward to today, you can see that the pricing on these bonds is significantly lower. What do you think that means to you as the consumer?
(And I want you to be quiet and listen because your customers are going to answer the question for you and they're going)
So, this is a professional-grade analytics site that I subscribe to. And the reason I do that is that I need these little locks. These are lock alerts that get sent to me to make sure that if you're under contract and we've decided to float for a while that we don't miss the market. And so I have people who are watching my back on your behalf.
Does that give clarity on how we approach the mortgage market?Describe the item or answer the question so that site visitors who are interested get more information. You can emphasize this text with bullets, italics or bold, and add links.
Mortgage Coach
I'm going to create a couple of different scenarios and potential solutions, and we're going to compare and contrast those based on the time horizon in which you plan on being in the property, and then we're going to revisit the assumption that the 30-year fixed is the best choice, because it may be, but I want to see how that nets out over a period of time, and I want to make sure you choose the loan with the lowest overall cost, including closing costs and interest over your time horizon. So when you get that link, take a minute to look through all the options, and then I want to schedule a time to circle back once you've had a chance to review it.’”
With your permission Prospect, I'm going to loop in your Realtor and/or financial advisor, because I want to make sure that the advice I give and the direction I'm advising aligns with your overall financial plan, and where your advisor thinks you should be going. I'm going to spell out the cost differences between the different loans, and we're going to look at the total costs over the time horizon you're going to be in the home. But I want to make sure whatever decision you make, you and your advisor feel good about. Would you make sure you have an opportunity to review this with your advisor before we make a final decision?
Pre-Approved Client Still Shopping Your Rate
I'm glad you took the time to call me back. I understand how you feel, wanting the best for your family.
One of my concerns, having been in this business as long as I have, is that, in an attempt to gain business, other lenders may often promise to meet or beat our rates. Or more importantly, that they can meet the close of escrow deadline.
Because of that, I don't like to play games. I believe in giving you the best deal upfront. Buying a home is enough work and the last thing you need is to play games with your mortgage company.
Besides, I have found that oftentimes these lenders charge higher fees in an attempt to make their rates look better.
And as a broker, I don't work for one bank, which means I work for you, not the bank. So when we talk about rates, it's not about what I'm offering; it's about what I found about 199 lenders that we are approved with.
Do you still want to work with me or do you want me to cancel your file?
(I know this might sound harsh, but if they are shopping for interest rates, this is a question to determine if they REALLY want to do business with you. Nothing is worse than processing the loan, and then they cancel because they are rate-shoppers and not committed to working with you.)
Pre-Approved with another lender
I know you’re already pre-approved, and I’m not looking to replace something that’s already working.
I simply want to make sure you have the right loan, the right rate, and the right overall strategy. And if your current lender already has the better deal, I’ll tell you that.
Buying a home is one of the biggest financial decisions you’ll ever make. Just like with major surgery, getting a second opinion makes sense.
Would you be open to a free second opinion?
I’ve been doing this for 25 years and have helped thousands of families. My job isn’t just to get you approved. It’s to help you structure the mortgage correctly, strengthen your offer, clear contingencies, and get you to the closing table.
I’ll compare what you have against a few things your current lender may not have shown you, including:
Your total long-term cost, seller-paid buydown opportunities, and ways to make your pre-approval more competitive.
And that last one can be important. Our pre-approvals are extremely thorough, and in a competitive market, the lender behind your offer can give the listing agent additional confidence that your financing is solid.
Would having that kind of advantage be valuable to you?
It costs you nothing to get a second opinion, and if you already have the best deal, I’ll be the first person to tell you
Should I lock?
Give market update and...
Markets react fast when bad news happens. Rates always go up faster than they go down, so when you are waiting for a drop you are exposed to a jump in rate.
I'm not a gambler and so my inclination would be to lock you right now and if the rates moves a very significant amount - .25
or .375, we can have a conversation about me helping you do a little bit better.
But you'll be protected from the downside.
Possibly remind them how tight things are, they have a lot of expenses coming up. The move costs money. The move always means five or six trips to Home Depot or Lowe's and it seems like each one of those trips is four $500.
Remember our closing numbers are pretty tight. If the market gets hit and your interest rate goes up, you might have to pay more money for the rate we targeted or need to qualify to close.
Open House: Prospects
“Welcome Home! Thank you for coming.
Did you see the home online, or drive by?
So how long have you been looking for a home?
How are you searching for properties now?
Have you seen any properties you liked?
Are you also looking in other areas?
Tell more about that.
If you bought the perfect home, how soon would you like to move in?
What is your price range?
Have you spoken with a lender and been Pre-Approved?
Would you like a second opinion on your borrowing options?
I know a few additional homes that are coming on the market would you like me to set up a showing? Hey guys, what did you think of the house?”When is the best time for you to go see that property?
Exactly What to Say Version
Rejection-Free Openings
1. I’m not sure if it’s for you, but we do have a special financing option for this house.
2. Are you open-minded to seeing what it takes to qualify?
3. Who do you know that has a house like this?
4. Opening-fact-question: Great to meet you. What do you like about this home?
Perspective Changers
5. What do you understand about this home?
6. What is your experience with buying?
7. How certain are you that this isn’t the right home for you?
8. How important is it for you to have a 4-bedroom 3 bath for you?
9. Could it be possible this is your dream home?
10. How would you feel if you lost this house?
11. Just imagine if you don’t find another home how will it impact you?
12. If this house sells, then will you still have a place to live? Assumptive Frames
13. When would be a good time to review if this is the house for you or not?
14. I'm guessing you haven't got around to see all the city has to offer.
15. You have three options.
a. Keep looking and hope we find a dream home and don’t get outbid.
b. Do nothing and keep renting.
c. Make an offer and let me negotiate the price down for you.
16. Two types of people
One who waited and lost the offer.
Secondly, those who make an offer and gain equity.
17. I bet you're a bit like me and don’t want to overpay in this market.
18. Simple swaps
a. Instead of looking at homes let’s discuss what you would want to change about this home to make it your dream home.
Open House: Neighbors
How long have you lived in the neighborhood?
Hey if you were to sell your home where would you move to?
How soon would you like to be there?
Tell me more about that.
Borrower In Process: CPA Call
Bill, one of the things that I find to be really important is that when I talk with a client about the indebtedness that they're going to be taking out the loan program and the terms associated, just like I've done with you right now, I need to check in and ask them how their relationship is with their CPA, and you consider your CPA to be someone who's a financial advisor to you.
If YES...
Wonderful. Sometimes I think it's valuable just to have a second set of eyes, especially somebody who's handling your taxes. What I'd like to offer to do and free of charge, I mean I, I'll take a little bit of my time, is just pick up the phone and contact your CPA, introduce myself, send them a copy of the spreadsheet that we just reviewed together and go over it and review it with him or her just to make sure that we're checking that box and that they feel that we're doing the right thing. That the amount of points that you're paying is the right amount of points, etc. Given your tax bracket and your tax deductibility.
If NO...that's a great opportunity for you to maybe make an introduction and refer them to a good CPA.
Call to the CPA
Call the CPA, and introduce yourself. Hi, Richard. My name's Tim Braheem with First Rate Financial. We have a mutual client in by the name of Bill Williams. I wanted to let you know that I'm going to be working on Bill's purchase transaction for his and his wife's new home. We've gone over three or four different loan scenarios in great depth and detail. We've kind of zeroed in on one Richard that I think makes the most sense, but we both agreed that just having your blessing, having a second set of eyes on it is really important, especially given the fact that he, he's going to be paying one and a half points. We want to make sure that you can fully write that off and that there are no issues there. You know much more about his tax planning strategies than I do, and I just want to make sure there are no blind spots.
Not ready to buy, doesn't want to complete the application
Explaining the value of starting Pre-Approval early
“What I found is a lot of home buyers don't see the importance of starting early with their financing so that they can get their ducks in a row to qualify for the best loan program and most competitive terms when the time comes to buy the house. The very minor impact to their credit to have the inquiry is very much worth what we can give as far as advice to help better situate you so you're ready for your home purchase six months, nine months, 12 months down the line. Is there anything that you have any concerns about before starting the conversation of kind of getting home ready?”
Tiktok Live
Presentation: https://www.canva.com/design/DAHQ5srKEto/Ut1DIVNJrz6GzInLTIJNmw/edit
On live, start talking right with an introduction so the algorithm knows who to show it to. Start who I am, what I do and what we are covering today
Try to turn every single question into a lead.
Schedule Appointments Scripts:
If you want to schedule a one-on-one just go to my bio and you can schedule one on one though my website
Fill out the form so we can continue this offline.
My website is in my bio. Also, If you want to schedule a one on one use talktoKurt.com
Send a dm with No Down and I will reach out
Stay Connected Scripts:
Do me a favor, hit that follow button so we can stay connected and you can see updates and more information
Drop a follow so we can stay connected.
I am doing this twice a week, so if you miss anything, come to my live again.
Please follow me so we can stay connected.
Fill out the form so we can continue this offline
Questions Scripts:
Hey btw, if you have questions be sure to ask them.
Please ask any questions you might have.
Hey btw, if you have questions be sure to ask them, if you want to send questions that I can answer offline or if you want to schedule a one on one just go to my bio and you can schedule one on one through my website
Hey Bob, great question! Hey everyone, this is a great question and it’s kinda important to understand…
Don't say that, Say this
Don't say "Pull Your Credit"
vs
Review Your Credit
Request Your Credit
or
Request and review Your Credit
Don't say "Your Rate.."
vs
Today's Rate Range is...
Don't say "You Qaulify for $XXX,XXX"
vs
Based on Fannie Mae guidelines, we need to keep your total payment at or below $4,300..... the payment can change depending the home, and where rates are, that why we always try to have a Pre-Offer Huddle.
Don't say "should be"
Will be
Don’t say "free"
On us
Don't say "easy"
Simple
Don't say "how are your?"
It's great to connect with you
Don't say "I'd love to..."
I'd be honored to carve out some time to...
Don't say "Thanks so much for your time."
I have enjoyed our time together.
or
I'm looking forward to our time together
Don't say "cash to close" or "cost"
Total Investment
Don't say "If you work with us...)
When we work together
Don't say "Buy a home"
Own a home
Don't say "What do you think?"
Are you ready to move forward?
I need to think about it
Totally fair.
Is there something that feels unresolved I rather you leave with clarity than doubt.
Then SHUT UP
We decided to go with someone else
Never say “I understand” or ask “why”. Say this, and it'll get you the next one.
Hey, totally fair, and thank you for telling me.
Two things: Can I ask you what they did that I didn't? And can I check back in 90 days and see how things are going?
That's the whole response. And here's why it's worth more than the deal that you just lost. Saying "I understand' closes the door politely. If you say why, it makes them defend a decision that they've already made, and then people who have to defend a decision will never call you back because that's all they think about you now. That first question gets you the truth because you asked about them, not about you. And the second one puts you on their calendar for the day that the other guy disappoints them, and he will about a third of the time.
So 90 days later, you were the one who was gracious, who asked, who checked in, and the other guy is just the one now who's late, and they're not happy with. Most people lose the deal, but then they also lose the relationship. That's short-sighted thinking. So if you lose the deal, keep the door open.
On the call back add them to Home Report and Stikkum and now you have a new Mortgage under Management.
How to Avoid The Most Dangerous 24 Hours in Lending
Why Buyers Panic Shop After Their Offer Is Accepted
The moment an offer gets accepted, something shifts. A buyer goes from excited to nervous almost overnight.
Why? Because now they feel like they've lost control. Appraisal fees, inspections, and closing costs suddenly feel out of their hands. So they do the one thing that feels like it gives them control back: they start shopping for a lower rate.
Why the old playbook doesn't work
Telling clients not to talk to other banks doesn't fix this. Neither does warning them about the risks or making them feel guilty for looking around. All of that puts the blame on the buyer instead of showing them why staying with you is the smarter move.
The fix: the Pre-Offer Huddle and the Offer Accepted Meeting
The real solution is proactive communication. Two huddles, done face to face or on Zoom, at the two moments that matter most: when the offer goes in, and when it gets accepted (same day or next day).
This turns the deal from a 30 day loan process into the first move in a 30 year wealth plan.
Watch: The Most Dangerous 24 Hours in Mortgage by Ryan Grant:
The Pre-Offer Huddle
Start by congratulating them. Then find out how much interest the property is getting, how long it's been on the market, and who the listing agent is.
Walk through the numbers and structure using Mortgage Coach
Cover
-A possible seller credit for closing costs
-A possible seller credit for a rate buydown
-Putting less down to keep cash available for investing, retirement, or renovations
Something like: "Let's walk through how holding back some cash versus putting more down affects your liquidity and your retirement plan over the next 5 to 10 years."
Review where the mortgage market stands using MBS Highway
Give them a clear, current read on rates and where things are headed. Show MBShighway
Walk through the Pre-Approval Strategy
Send an online loan presentation with a video overview (Mortgage Coach Single Option https://mcedge.tv/zjo5js) to the listing agent by email and text
Confirm the pre approval letter amount: Does the buyer's agent want it to show the max or the actual offer price?
I personally reach out to the listing agent by email, text, and phone. Many times you already know them or have closed a deal together before.
This Pre-Approval Strategy tells the listing agent a few important things:
The buyer's due diligence is already done
The buyer is fully approved, not just pre qualified
The deal is set up to close smoothly and on time
The buyer has a local, hands on team behind them, not an out of state lender scrambling mid deal
The offer stands out from the rest
Closing for the Accepted Contract Huddle
"Once your offer is accepted, one of the most important things we do is meet face to face within 24 hours. We'll protect your money, lock in the right rate and term, and put the contract, payment, cash needed, and timeline right on the screen so we can pick the right strategy together. We'll also walk through what happens next."
Th Offer Accepted Meeting
"Congratulations! Huge moment! Our entire team is so glad we could help you get this home. Now that your offer is accepted, we begin the most important financing strategy window of the transaction. I have a few time slots available today/tomorrow for our contract meeting..."
Before we dive into the numbers and loan details, I just want to pause and say congratulations! Think back to when we first talked—you weren't even sure if buying a home was going to be possible this year, and now here we are with an accepted offer. How are you feeling right now, and what are you most excited about with this house?
Follow and use this: https://docs.google.com/document/d/1KjqNVZdoJm_U-hwa9-oM4igN5MM-Mie6/edit